
Think of your state pension like a shared Netflix account. If you die, the subscription doesn’t automatically cancel for your spouse—they might still get to watch a few episodes. But if you’re single, the account just goes dark.
The big question is: did you build your pension on your own record, or do you have a partner who also paid in? The answer decides everything.
If you’re married or in a civil partnership
Your partner might be able to inherit a chunk of your state pension. It’s not the full amount, but it’s something. Think of it as a little financial hug from beyond the grave.
Specifically, your spouse can get a lump sum of £5,000 if you were receiving a state pension when you passed. Plus, they might get a small boost to their own pension—up to about £10 per week extra, depending on the rules at the time.
Here’s the catch: this only works if your partner hasn’t already claimed their full state pension. It’s like getting a coupon that only works if you haven’t already bought the store.
If you’re single, widowed, or divorced
Sorry, but your pension dies with you. No spouse, no partner? The state pension stops completely. No one gets that money, not even your kids or your favorite niece.
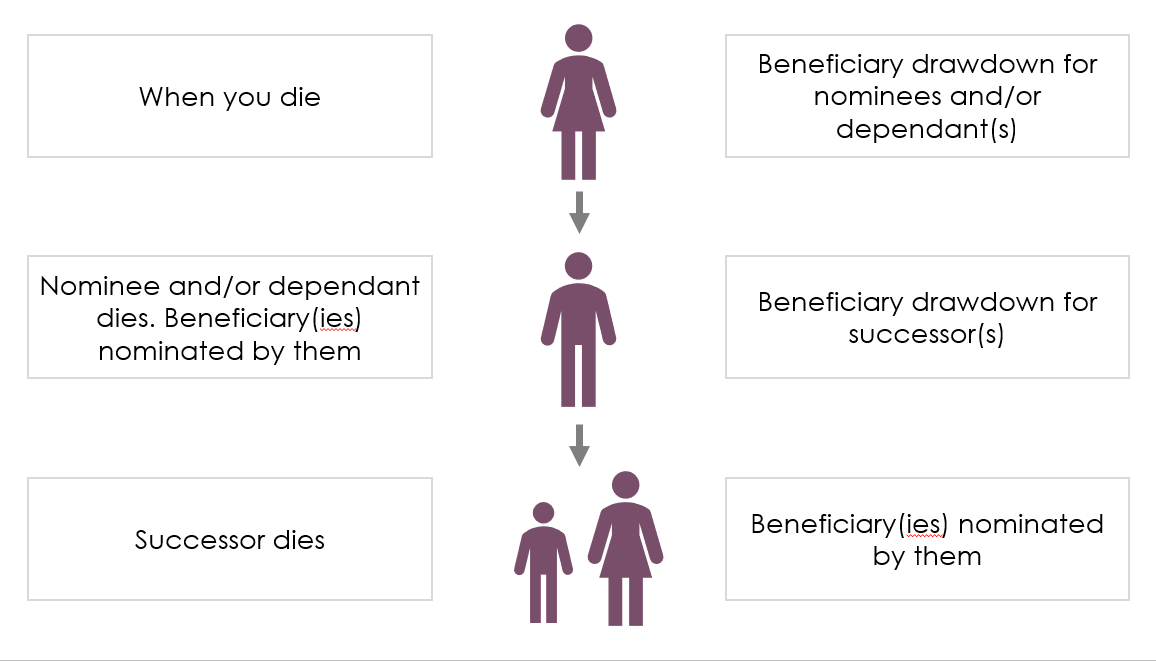 What happens to my pensions after death? | The Private Office
But hold on—if you have children under 16 (or up to 20 if they’re in full-time education), they might still be eligible for child benefit increases tied to your record. So your pension doesn’t totally ghost your family.

