Here’s where it gets sticky. If your Uncle Dave was already collecting his monthly pension check, that check stops the month he dies. Yes, you cannot keep cashing it. The pension company will send a final payment, and then it’s done—like a TV show that ends on a cliffhanger. If Dave chose a “joint and survivor” option (meaning it keeps paying his spouse), then his wife, Aunt Linda, gets 50% to 100% of that check for the rest of her life. Smart Dave.
But if Dave chose a “single life” option to get bigger checks while he was alive? When he goes, the pension goes kaput. It’s like ordering the giant bucket of popcorn but forgetting you have to share the bathroom later. Spouses should always, and I mean always, ask about this before retirement. Nobody wants to learn about survivor benefits while holding a casserole and a calculator.
The Tax Man Cometh (Of Course)
You thought you could just take the money and run? The IRS wants a dance. If the pension is a lump sum paid to a beneficiary, it’s taxed as ordinary income for that year. Imagine getting a bonus at work, except the bonus is your dead uncle’s retirement fund. It can push you into a higher tax bracket faster than you can say “I hate April 15th.”
But here’s a little trick: if the beneficiary is a spouse, they can roll the pension over into their own IRA without any tax hassle. It’s like transferring your leftover pizza to a new box—no waste, no mess. Non-spouse beneficiaries, like your cousin Kevin, have to take the money out within ten years, per the SECURE Act. Kevin will probably use it for a down payment on a van to live in.
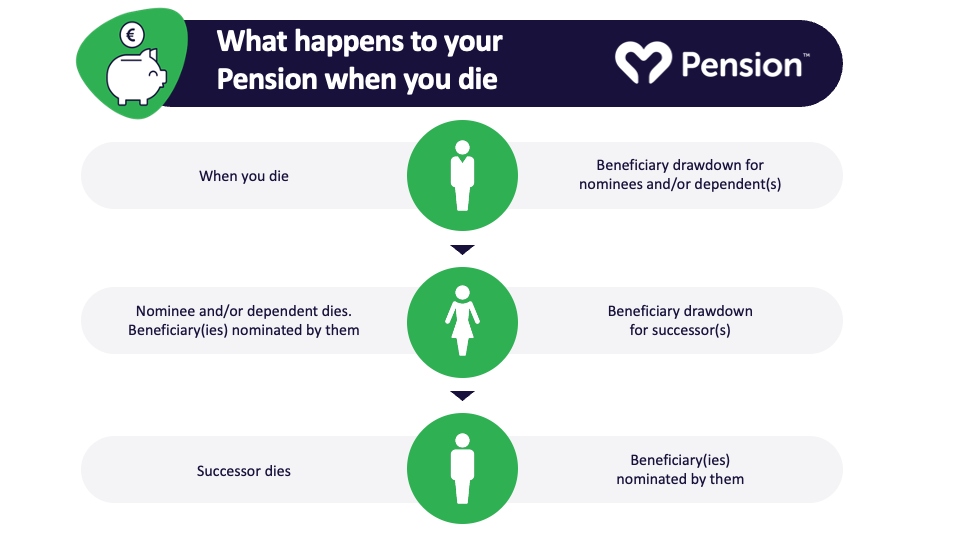 What Happens to My Pension When I Die? - MyPension

