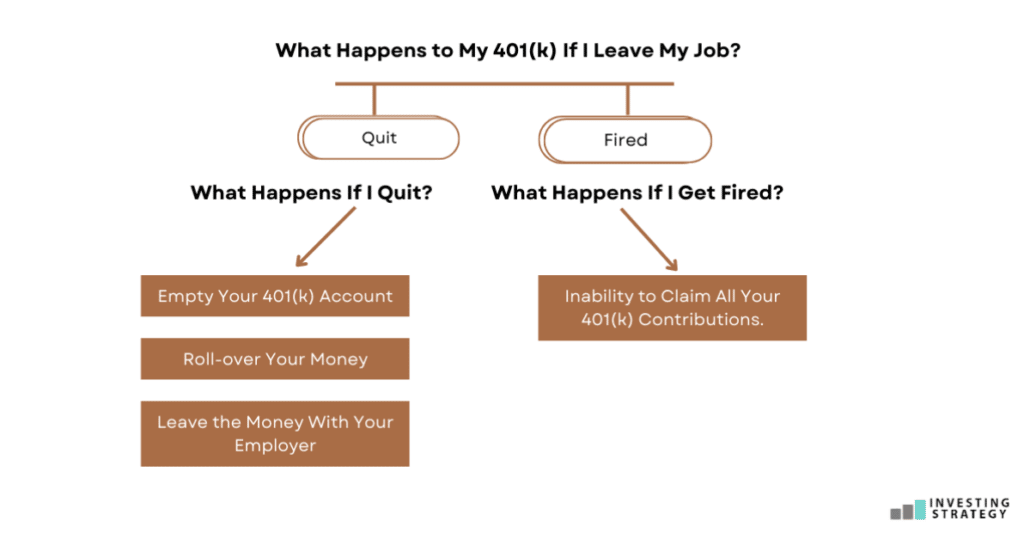
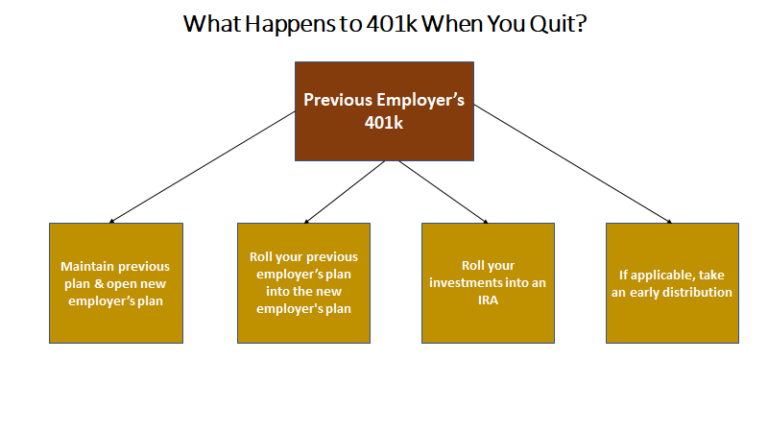
This is the hero move, the “I read the manual” choice. You take your 401k and roll it over into an IRA (Individual Retirement Account) at a brokerage like Vanguard, Fidelity, or Schwab. Why? Because you become the boss of your money. You can choose any investment—stocks, bonds, even a mutual fund that only buys companies that make dog toys. The fees are usually lower, and you have total control.
It’s like taking your money out of a boring beige cubicle and moving it into a cool hacker loft. You can even roll it into your new employer’s 401k, if they have one. Just make sure the transfer is a “direct rollover.” The money goes straight from one account to the other, without touching your hot little hands. If you take a check yourself, the taxman will be waiting outside your door, licking his chops.
But Wait—There’s a Secret Bonus
Roth 401k accounts? If you had one, you can roll that into a Roth IRA. And here’s the joke: all your contributions are already taxed, so the growth is tax-free forever. It’s like planting a tree that grows dollar bills, and the IRS just waves at it from a distance. But if you roll a regular 401k into a Roth IRA, you have to pay taxes on the conversion. Ouch. Do your homework, or ask a tax guy. Seriously.
 What happens to 401k when you quit?

