
Your tax-free allowance isn’t a permanent number carved into a stone tablet. It can be adjusted for various reasons. For example, if you have untaxed income from savings interest or a side hustle, HMRC might reduce your code to collect the tax later. It’s their way of balancing the books without sending you a scary letter.
Also, if you claim Marriage Allowance or have a company car (a “benefit in kind”), your allowance gets tweaked. This is why your tax code changes sometimes. Don’t panic—just check it every year. Think of it like your allowance going on a mini-diet or a small binge, but the basics stay the same.
One brilliant bit: if you don’t use all your allowance in a tax year, you might be able to carry forward some unused bits if you’re self-employed or have certain savings rules. But for most employees, it’s a “use it or lose it” situation. So, earn that £12,570 with pride—it’s free money, really.
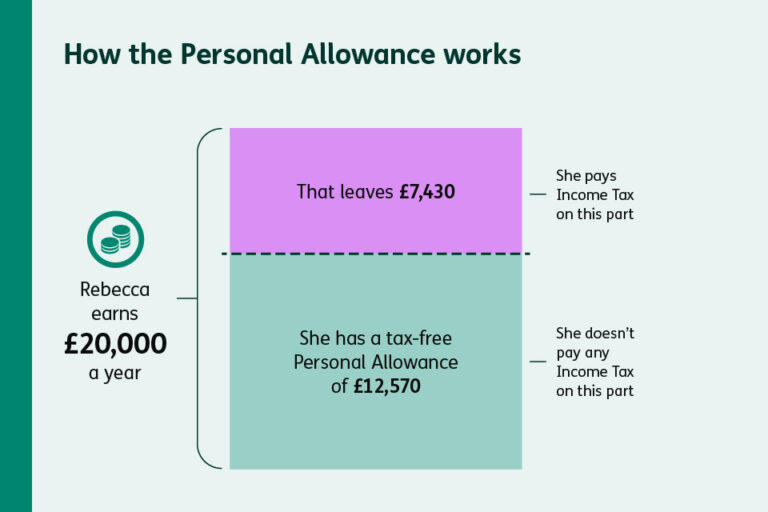 What is a Tax-Free Personal Allowance? - Tax Confident
A Quick Note on Savings and Dividends
Wait, it gets even better. On top of your Personal Allowance, you can earn up to £1,000 in savings interest completely tax-free (if you’re a basic rate taxpayer). That’s the Starting Rate for Savings. If you’re a higher rate taxpayer, it’s £500. Nice little bonus, like finding an extra slice of toast under the grill.
And if you own shares? You get a Dividend Allowance of £1,000 (it’s currently decreasing to £500 from 2026/25, so don’t snooze on it). So, your tax-free allowance isn’t just one thing—it’s like a three-tiered cake of “keep your money.”

