
Your 401(k) is different: it’s your money, not the company’s promise. If you die, whoever you listed as a beneficiary gets the whole enchilada. But here’s the ugly twist: if you named your estate instead of a person, the taxman might take a bigger bite. Pro tip: name a human, not your will.
Now, what if you never got around to withdrawing any of it? Your heirs can inherit the account as an Inherited IRA, and they have to take it out within 10 years. That means they might get hit with a tax bill on a giant pile of money all at once. Not the worst problem to have, but still a headache.
The "What About Social Security?" Question
Social Security isn’t a pension in the strict sense, but people lump it in. If you die, your spouse might get a survivor benefit—but only if they’re old enough or caring for a minor child. If you’re divorced and married for 10+ years, same deal. But here’s a weird one: if you never claimed benefits, your spouse gets zilch. Timing matters.
And if you’re single with no kids? The government just pockets your contributions. It’s like paying for a pizza you never get to eat, and no one gets the leftovers. I call that the "cosmic irony" clause.
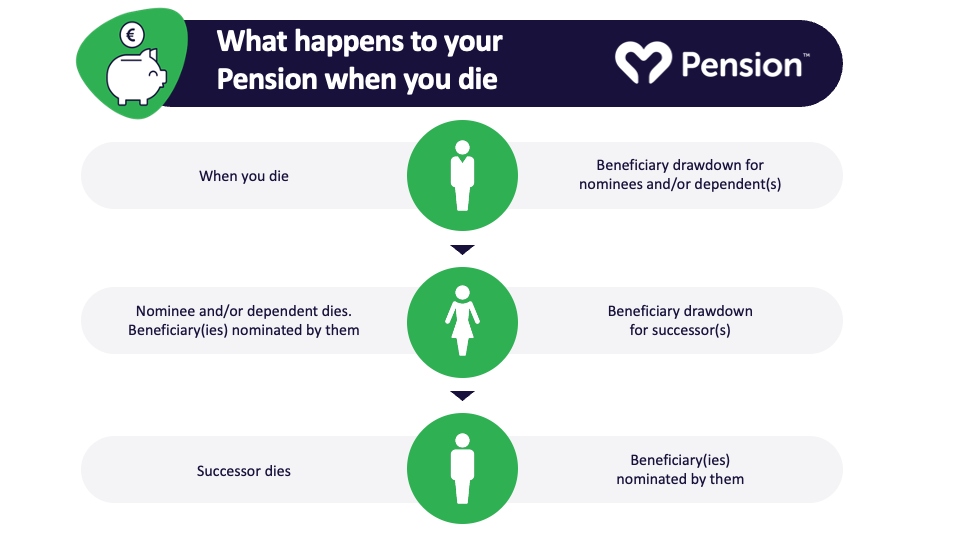 What Happens to My Pension When I Die? - MyPension

